Built by LOs, for LOs

Loan comparisons made clear.

Give borrowers a clean side-by-side view of Conventional, FHA, VA, USDA, purchase, and refinance options with real closing cost breakdowns and a borrower-ready presentation.

Or open the calculator and try it — no account needed.

✓ 7-day free trial
✓ No credit card
✓ $27/mo after
reports.ask.mortgage Real figures
Option 1
20% Down / Par Rate
Conventional · 30 Year Fixed
$5,320Estimated Monthly Payment
Lowest Upfront Cost
Interest Rate
7.375%
APR
7.430%
Cash to Close
$185,803
Option 2
20% Down / 1 Point
Conventional · 30 Year Fixed
$5,158Estimated Monthly Payment
Lowest Monthly PaymentLowest Rate
Interest Rate
6.999%
APR
7.153%
Cash to Close
$192,104
Option 3
10% Down / Par Rate
Conventional · 30 Year Fixed
$5,993Estimated Monthly Payment
Lowest Cash to Close
Interest Rate
7.375%
APR
7.424%
Cash to Close
$106,485
Option 4
10% Down / 1 Point
Conventional · 30 Year Fixed
$5,810Estimated Monthly Payment
Lowest RateLowest APR
Interest Rate
6.999%
APR
7.147%
Cash to Close
$113,574
How each option compares against the 20% down par-rate baseline, from the published sample report.
Baseline20% Down / Par RateConventional · 30 Year Fixed Option 220% Down / 1 PointConventional · 30 Year Fixed Option 310% Down / Par RateConventional · 30 Year Fixed Option 410% Down / 1 PointConventional · 30 Year Fixed
Monthly Payment $5,320 $5,158−$163 $5,993+$673 $5,810+$489
Cash to Close $185,803 $192,104+$6,301 $106,485−$79,318 $113,574−$72,229
Interest Rate 7.375% 6.999%−0.376% 7.375%Same 6.999%−0.376%
APR 7.430% 7.153%−0.277% 7.424%−0.006% 7.147%−0.283%
Mortgage Insurance - -Same $120+$120 $120+$120
Total Closing Costs $25,803 $32,104+$6,301 $26,485+$682 $33,574+$7,771

Every option, figure and difference above is taken from a real published report, not a mock-up. Open the sample (opens in a new tab)

What’s Included

Everything a loan officer needs in one clean comparison.

Built around the way real loan conversations happen: payment, cash to close, rate, APR, MI, funding fees, credits, points, and the practical reason one option may fit better than another.

Side-by-side scenarios
Compare up to four loan options at once with independent loan type, rate, term, price, loan amount, down payment, and closing cost inputs.
Borrower-ready clarity
Use the tool to explain the tradeoffs without burying the borrower in raw numbers or hard-to-read spreadsheet outputs.
PDF-ready presentation
Create cleaner borrower-facing summaries that feel like a professional loan proposal, not a browser printout.
Closing cost breakdowns
Show lender fees, credits, points, prepaid items, escrow reserves, title fees, recording costs, and estimated cash to close.
MI, MIP, and funding fee logic
Compare Conventional PMI, FHA MIP, VA funding fees, and USDA guarantee fee differences in one place.
Purchase and refinance
Use the same comparison framework for purchases, rate/term refinances, cash-out, FHA streamline, and VA IRRRL scenarios.
The borrower report

You send a link. It has your name on it.

Not a PDF attachment they lose in a text thread. A live, branded report your borrower opens on their phone — and can still print or save as a PDF when they want one.

  • ✓ Your branding, automatically Your name, photo, NMLS, company, licensed states, and an Apply Now button that goes to your application.
  • ✓ English or Spanish Every borrower report opens in either language. One toggle, same numbers, same branding.
  • ✓ Built for a phone Most borrowers open your report on the same device they texted you from. It is designed for that first.
  • ✓ You stay in control Links are yours to share, update, or archive. Archiving a report takes its link offline immediately.
Open a sample report (opens in a new tab)
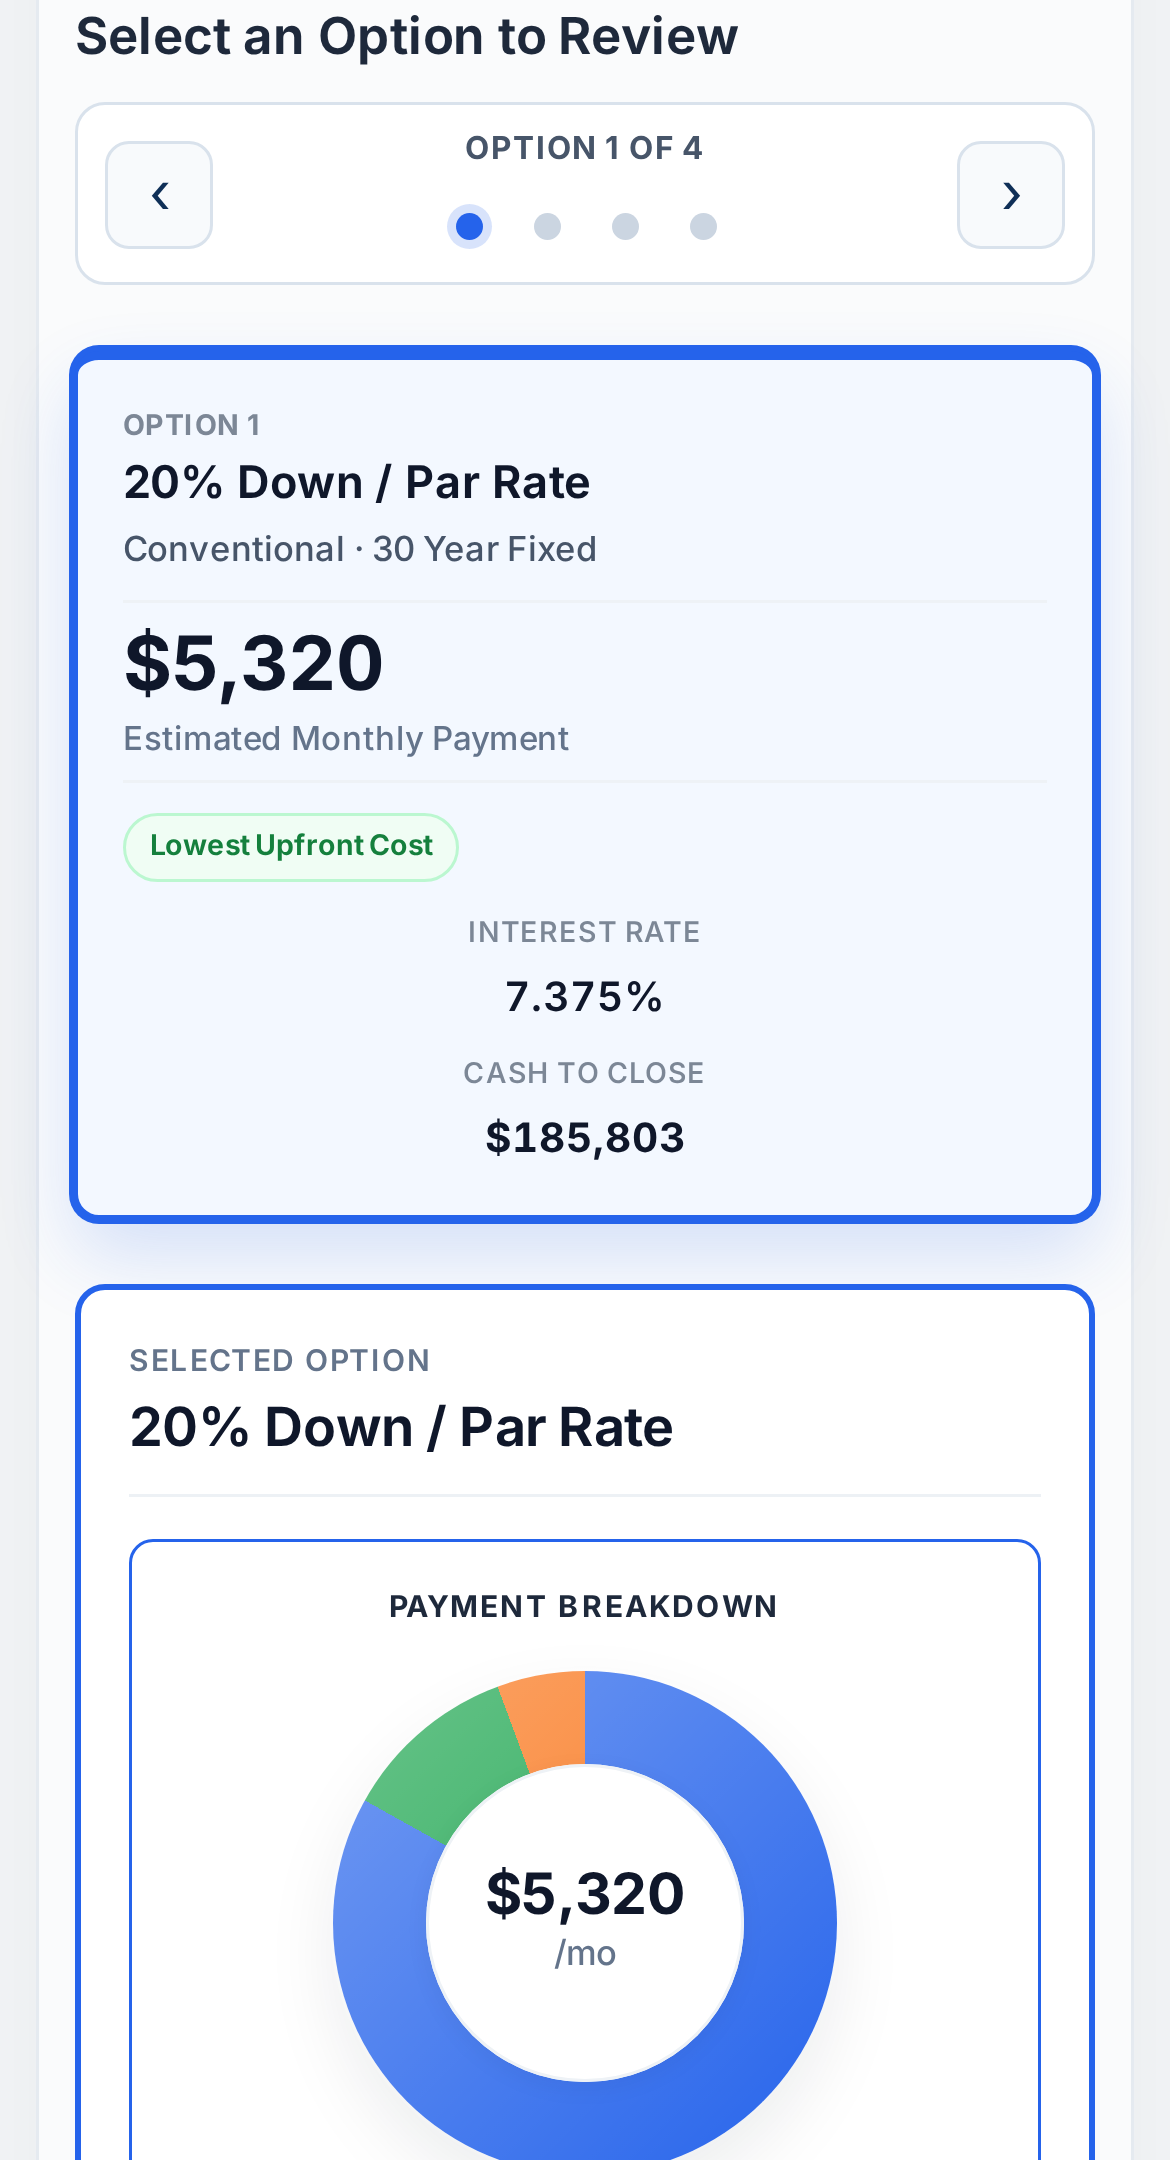
The borrower report on a phone: an option carousel showing 20% down at a 7.375% rate, a $5,320 estimated monthly payment and $185,803 cash to close, above a payment breakdown chart.
Workflow

From loan quote to clear borrower decision.

Open the tool, build the options, explain the tradeoffs, then share or save the comparison for the borrower.

1
Enter the scenario
Start with purchase or refinance details, property state, price or value, FICO, loan type, rate, and term.
2
Add loan options
Compare Conventional, FHA, VA, USDA, different rates, down payments, credits, or pricing structures.
3
Review the tradeoffs
See monthly payment, cash to close, APR, MI, fees, and key differences side by side.
4
Share the answer
Use the clean output to help the borrower understand which option fits their goals best.
Loan Programs

Built for the comparisons borrowers actually ask about.

The goal is not just to show numbers. It is to help a borrower understand why a loan option may be better for payment, cash to close, qualification, or long-term fit.

Agency
Conventional
Fannie Mae and Freddie Mac comparisons with PMI, conforming and high-balance structure, and flexible down payment inputs.
Government
FHA
Upfront MIP, annual MIP, streamline logic, and lower down payment comparisons for borrower conversations.
Veterans
VA
Zero-down structure, funding fee logic, first-use inputs, and IRRRL scenarios without PMI confusion.
Rural
USDA
100% financing structure with upfront guarantee and annual fee assumptions shown clearly.
Refinance
Rate/Term
Show lower payment, term changes, estimated value, payoff balances, and break-even style conversations.
Equity
Cash-Out
Compare cash-out proceeds, new loan amount, payment impact, and estimated closing cost differences.
Pricing

$27 a month per loan officer.

Every feature at every size, unlimited comparisons and borrower reports. Start with a 7-day free trial — we do not ask for a card to begin.

Annual
$270/yr

Two months free compared with monthly. We email you a reminder before every renewal.

Start free trial
Everything is included
✓ Unlimited comparisons and saved reports
✓ Up to 4 loan options side by side
✓ Purchase and refinance
✓ Conventional, FHA, VA, and USDA
✓ Branded borrower links
✓ English and Spanish reports
✓ Print and PDF output
✓ Contacts and saved reports
✓ Reusable templates and default fees
✓ Tutorials and support
What happens when the trial ends? Nothing is charged, because we never collected a card. Publishing new borrower links pauses until you subscribe. Your reports, contacts, and settings stay exactly where they are — and any borrower link you already sent keeps working.
Free guide

The Ask.Mortgage loan officer guide.

Every feature, walked through end to end — building a comparison, branding it, sending the borrower link, and the Spanish version. Not ready to start a trial? Read this first.

One email with the guide. No drip campaign unless you ask for one, and you can unsubscribe from any message.
Questions

The things loan officers ask first.

Do I need my company's approval to use this?
No. It is your own account at $27 a month, with your own branding on the output. Nothing has to be installed, provisioned, or approved by anyone. If your office would rather hold one account for everybody, that is what the Team pricing is for.
Does it replace my LOS or my CRM?
No, and it is not trying to. Ask.Mortgage is the comparison conversation that happens before the application — you keep originating wherever you originate today.
Where do the rates and fees come from?
From you. Ask.Mortgage is not a pricing engine and does not quote rates. You enter the rate, points, and fees you are actually offering; we handle the math, the mortgage insurance and funding fee logic, and the presentation.
Can I use my own fees and defaults?
Yes. Save your standard lender fees, title and recording assumptions, and typical scenarios as reusable templates, so a new comparison starts from your numbers instead of ours.
Can my borrower read the report in Spanish?
Yes. Every borrower report opens in English or Spanish from the same link — same figures, same branding, one toggle.
Is my borrower's information safe?
Borrower reports are reachable only by their own private link, and archiving a report takes that link offline immediately. See our privacy policy for how data is stored, exported, and deleted.
Do you need a credit card to start the trial?
No. The 7-day trial collects no payment method at all, so there is nothing to charge when it ends and nothing to cancel if you decide against it. Team plans work the other way round: a seat is not on a trial, because the company has already decided — seats go live when the first invoice clears and the officers themselves are never asked for a card. Setting the account up is still free: you create your own account and build the roster before anything is collected.
How do I cancel?
From Settings, in two clicks. Access continues through the end of the period you already paid for. There is no prorated refund for unused time, and no cancellation fee.
Ready to compare?

Build your first comparison in about two minutes.

Seven days free, no credit card. Then $27 a month if you keep it — and your borrower gets a report they can actually read.

Start free — no card →
ask.mortgage app icon